While the election postmortems continue to grab attention, the financial headlines are increasingly focused on the next major vote, which will be cast by the 12 members of the Federal Reserve Open Market (FOMC) on December 8-9. The polls strongly indicate that a rate hike at the confab is a sure thing. The only question is by how much. Governor Waller and several other policy makers went on record with hawkish comments this week, with Waller apparently lending support to a half-percent hike. That, in combination with the quarter-point increase taken in September, would fully erase the three-quarter percentage point insurance cut the Fed took in 2025. Other officials also chimed in favoring a tightening move, although they were generally supportive of a more gradual approach, raising rates by smaller quarter-point increments.
Whether a “shock and awe” policy decision is appropriate or not is an open question, and a case can be made either way. Some believe that an increase should have been taken at the October meeting, when the Fed opted to stand pat and monitor the effects of the September hike. Waller’s comments can be seen as a desire to catch up with events that were unleashed by inaction at the September meeting. The post-meeting data since then would seem to justify that case. Job growth has exceeded expectations, and inflation has come in hotter than expected, as confirmed by this week’s price reports. Meanwhile, the war in Iran has not been resolved, energy prices remain elevated and their knock on effects on broader inflation are still phasing in and are likely to continue for months to come.
But the case for a more gradual approach is understandable, given the fog of uncertainty that overhangs the landscape. The strongest case against a more strident policy was promoted by the noted monetary economist Milton Friedman in the last century, when he likened an outsized rate move in either direction to the fool taking a shower. The water may seem too cold at first but the kneejerk reaction to yank the faucet too far hot will result in severe burns. Simply put, the water temperature does not change right away, and its delayed response requires a more gradual turning of the valve to reach a comfort zone. That lagged effect is a time-honored principle well known to the Federal Reserve but is not always followed, resulting in unwanted consequences down the road.
To be sure, the principle applies in both directions, as waiting too long to turn the heat up risks falling behind the inflation curve. That risk is gaining traction among policymakers and is the primary reason most are leaning towards raising rates at the next meeting. The impetus behind that more hawkish sentiment received a big boost with the stronger than expected October jobs report, which confirmed that the economy has enough resilience to withstand higher rates.
With the goal of achieving maximum employment satisfied, the Fed could focus on the other half of its dual mandate, achieving price stability around its 2 percent target. That mission is far from accomplished.
Waller and some other Fed officials indicated that should core consumer prices increase by 0.3 percent or more in October, it would confirm that inflation is still too hot and warrants a tough reaction. The CPI report this week met that threshold for the third consecutive month and lifted the increase over the past year from 2.6 percent to 2.8 percent. The annual increase is calculated off of an interpolated base, as the government shutdown prevented the Bureau of Labor Statistics (BLS) from compiling the October data last year. But the near term trend showed a more worrisome increase, as the advance over the past three months spiked from a 3.4 percent annual rate in September to 3.7 percent last month, the fastest clip since April 2024.
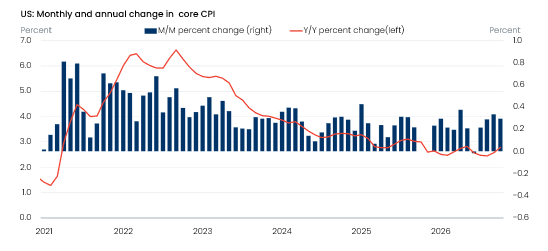
Importantly, the accelerated inflation pace does not reflect ongoing supply shocks, as the tariff impact is waning and energy price increases slowed considerably, rising by 0.7 percent in October compared to 5.2 and 2.1 percent in September and August. The lagged effects from the war-induced surge in energy prices will continue to pass through to food and other prices in coming months, but that too should fade if hostilities end and global oil prices stabilize – a big if. That said, from the Fed’s perspective, its main inflation-fighting tool, changing the short-term policy rate, is more effective in curbing demand than supply.
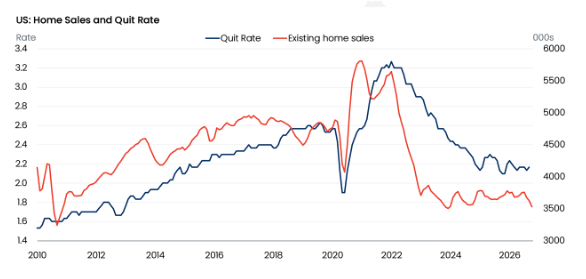
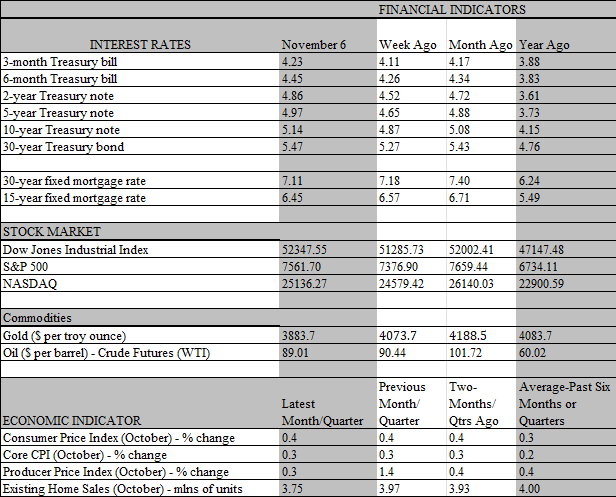
Hence, to take heat off of prices, its only option is to create some slack in the economy by weakening demand. But that option is complicated by the fact that a growing tailwind propelling growth is coming from sectors, most notably those linked to the AI boom, which are less sensitive to rate increases than those that have historically led the way cooling off the economy. The question then is how much slack from the rate sensitive sectors needs to be created to cool off the broader economy? Clearly, the most vulnerable industry is housing, which is already in the doldrums and where affordability has already been severely eroded due in good part to high mortgage rates. In September, existing home sales fell to the lowest level since 2010, as mortgage rates north of 7 percent have pushed both sellers and buyers to the sidelines.
On the surface, home sales should not languish as badly when the economy is at full employment unless lenders shut off the mortgage spigot due to balance sheet impediments or other supply-side constraints. However, this is not a garden variety full employment environment, but one that is dominated by low hiring, low firing and low quitting. This is a classic portrait of a stagnant labor force, where a lack of churn translates into a less dynamic and productive economy than would otherwise be the case. No doubt, this condition is the product of several forces, including demographics (an aging population) and immigration policies.
Yet there is also a connection between worker mobility and labor turnover, and a key link is the housing market. If people are stuck in their homes they can’t move to areas where job opportunities are more plentiful or more productive. The bad news for housing is that mortgage rates are likely to stay above 7 percent for some time. Indeed, the modest decline in recent weeks is poised to be fully reversed, reflecting a sharp increase in the 10-year Treasury yield this week against which mortgage rates are loosely benchmarked. The best hope for a frozen housing market is that inflation recedes and ushers in lower bond yields. But how much slack needs to be created to bring that about is the critical issue the Fed will grapple with in upcoming meetings, beginning next month.